


Key Divorce Mortgage Planning Lessons from the HCBA CLE
From Settlement Language to the Closing Table: Decisions That Shape Divorce Mortgage Outcomes
Divorce mortgage outcomes rarely happen at the closing table — they usually begin much earlier, at the settlement‑drafting stage.
That was the central theme of our recent HCBA CLE, From Settlement Language to Closing Table: Pre‑Application Decisions That Affect Divorce Mortgage Planning Outcomes. My portion of the session focused on how decisions made during settlement negotiations directly affect whether a post‑divorce refinance, equity buyout, or purchase will actually fund.
Below are the five key takeaways from the presentation, paired with the most common planning assumptions that break down at underwriting, so family law attorneys can spot — and avoid — execution problems before an agreement is finalized.
#1: Debt Allocation Language Must Align With Credit Reporting Reality
Assigning responsibility for debt in a Marital Settlement Agreement does not automatically resolve how that debt is treated for mortgage qualification. From a lender’s standpoint, clarity and specificity matter as much as intent.
Joint obligations remain visible on both credit reports until refinanced or paid off. Authorized user accounts can continue to affect credit scores until they are removed. Even when debt payment responsibility is assigned by court order, underwriting outcomes depend on whether the obligation can be clearly identified and documented.
What Often Assumes vs. What Underwriting Requires

| Settlement Assumption | Mortgage Underwriting Reality |
|---|---|
| Debt assigned to one spouse | Specific tradeline must be identifiable |
| Narrative descriptions are sufficient | Account numbers govern underwriting |
| Court order excludes the debt | Missed payments may still impact credit |
Drafting Insight: Credit reports do not recognize descriptive labels like “the blue BMW loan.” If the lender cannot link the obligation to a specific tradeline, the debt may still count against qualification.
#2: Credit Strategy Is Most Effective Before the Application Is Filed
Credit issues may not be able to resolve themselves within court‑imposed refinance deadlines. However, small targeted actions taken before a loan application is submitted can materially impact eligibility.
Credit rescoring (often referred to as rapid rescoring) may be used to reflect updated information after:
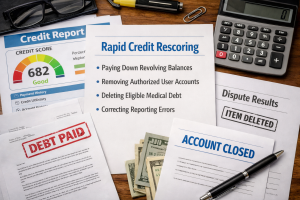
- Paying down revolving balances
- Removing authorized user accounts
- Deleting eligible medical debt
- Correcting reporting errors
This is not credit repair, and results vary by borrower profile, but timing is critical.
What Often Assumes vs. What Underwriting Requires
| Settlement Assumption | Mortgage Underwriting Reality |
|---|---|
| Credit will improve on its own | Scores are evaluated at application |
| Deadlines drive approval | Credit profile drives approval |
| Fixes can occur post‑denial | Many changes require lead time |
Practice Tip: Credit strategy works best as prevention, not remediation. Once underwriting begins, options narrow quickly.
#3: Loan Program Selection Drives Equity and Timing
Not all loan programs provide the same flexibility for divorce cases. Program selection can significantly affect:
- How much equity is available
- Credit and debt‑to‑income flexibility
- Whether refinancing is feasible at all
VA loans, for example, allow higher loan‑to‑value limits and more flexible underwriting standards than many conventional programs. Self‑employed borrowers may require alternative documentation strategies if traditional income no longer reflects post‑divorce cash flow.
What Often Assumes vs. What Underwriting Requires
| Settlement Assumption | Mortgage Underwriting Reality |
|---|---|
| Equity equals appraised value | Equity limited by program LTV caps |
| All borrowers qualify the same way | Program rules vary widely |
| Income is “good enough” | Documentation standards control |
#4: Equity Buyouts Are Mortgage Transactions — Not Simply Transfers
An equity buyout is not a cash‑out refinance. It is a feature of a rate‑and‑term refinance governed by strict underwriting rules.
To qualify, settlement agreements must clearly state:
- Which spouse is retaining the home
- The exact amount or percentage of equity being paid
- That proceeds are distributed solely to the departing spouse
The spouse retaining the property may not receive cash back for any purpose.
What Often Assumes vs. What Underwriting Requires
| Settlement Assumption | Mortgage Underwriting Reality |
|---|---|
| Buyout equals cash‑out | Must fit rate‑and‑term guidelines |
| Flexible fund distribution | No borrower cash back permitted |
| General language is acceptable | Precision is mandatory |
#5: Drafting Details for Timing & Title Insurance Reminders
Even when qualification is possible, execution can fail due to overlooked drafting and timing issues. Common pressure points include:
- Aggressive refinance deadlines that ignore underwriting timelines
- Quitclaim deeds lacking explanatory language
- Refinancing homestead property prior to final judgment
What Often Assumes vs. Loan Underwriting Timelines and Title Insurance
| Settlement Assumption | Mortgage and Title Reality |
|---|---|
| Refinance timing period | Full underwriting timeline applies |
| Deed language is secondary | Potential Transfer Tax Issues |
| Both parties must sign | Joinder may be appropriate |
Final Thought
Divorce mortgage planning succeeds when legal objectives and lending mechanics are aligned early. Attorneys who account for credit, debt structure, loan programs, equity rules, and timing during the drafting phase dramatically reduce post‑judgment disputes and failed refinances.
The most efficient closing is almost always the one that was planned before the agreement was signed.
Need Help Pressure-Testing a Refinance Timeline Before Settlement or Post-Judgment?
Our Second Opinion Service (SOS) can help—provided at no cost to support your case strategy.
An SOS review includes:
- A full review of the client’s credit profile
- Guidance on how each account type will be treated for mortgage qualifying
- Simulated credit score and DTI ratio changes before decisions are made
- Identification of hidden mortgage qualification risks
- Recommendations on how to align the marital settlement agreement with mortgage guidelines
Request your confidential review so credit timelines are addressed before settlement terms are finalized.
Call/Text: 813-935-8330
Office: 800-806-9836 Ext. 280
Email: SeanS@MPLX.org
And don’t forget—download your complimentary copy of our Divorce Lending Blueprint for Success to keep as a resource for both you and your clients.

Sean A. Stephens, Esq., CMB®, CDLP®
President | Chief Legal Officer
Metroplex Mortgage Services, Inc.
Legal Disclaimer: The information provided on this blog does not, and is not intended to, constitute legal advice; instead, all information, content, and materials available on this site are for general informational purposes only. No representations or warranties of any kind, express or implied, are made about the completeness, accuracy, reliability, or availability of this information. Metroplex Mortgage Services, Inc. is not a law firm and does not provide legal services. Sean A. Stephens is a member of the California State Bar #332960 and Florida Authorized House Counsel #1027099 for Metroplex Mortgage Services, Inc. Florida Authorized House Counsel may provide legal services in Florida solely to the employing business organization but is not authorized to practice law in the state of Florida and is not a member of the Florida Bar.


