


After HCBA Bench Bar: Key Mortgage Issues to Check Before Settlement
Supporting Family Law Attorneys With Practical Refinance, Income, Credit, and Mortgage Planning.
As a follow-up to our recent sponsorship at the Hillsborough County Bar Association’s 29th Annual Bench Bar Conference at the JW Marriott in Tampa, I wanted to share several of the mortgage planning issues that came up in conversations with family law attorneys during the event.
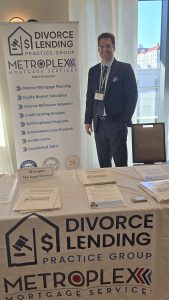
Proud to support the family law community—Metroplex Mortgage Services’ Divorce Lending Practice Group at the HCBA Bench Bar Conference on October 22, 2026.
It was a valuable opportunity for our Divorce Lending Practice Group at Metroplex Mortgage Services, Inc. to connect with family law attorneys and discuss the mortgage-related questions that arise when clients are navigating divorce.
Our conversations included divorce refinance options, self-employed income situations, credit scoring, and the challenges that can affect a client’s ability to retain the marital home or purchase a new residence.
Thank you to everyone who stopped by our table. Below are several practical planning considerations connected to those conversations, along with resources for attorneys and their clients.
1. Divorce Refinance Options Should Be Evaluated Before Settlement
When a client wants to retain the marital home, agreeing on the equity distribution is only part of the process. The next question is whether the client can qualify for financing that supports the proposed settlement.
The equity buyout is the objective; refinancing is a tool used to fund it. A properly structured equity buyout may qualify for limited cash-out or rate-and-term treatment rather than a standard cash-out refinance. Depending on the loan program and borrower qualifications, this may provide more favorable interest rates and higher loan-to-value limits, helping maximize the equity available for settlement.
That distinction can affect loan terms and the amount of financing available. Ownership requirements, settlement language, and the proposed distribution of refinance proceeds should be evaluated before assuming that a particular payout can be funded.
The marital settlement agreement should clearly identify which spouse will retain the property, the amount or percentage of equity payable to the departing spouse, and how the distribution will be accomplished.
Planning Tip: Review the available financing and anticipated monthly payment before negotiating the equity payout and refinance deadline. A property may have substantial equity without the retaining spouse qualifying for the loan needed to access it.
For a closer look at the financing structure and settlement provisions, read Florida Equity Buyout Refinance: 3 Costly Mistakes Attorneys Must Avoid.
2. Self-Employed Clients Need More Than a Quick Look at Their Tax Returns
A business owner may have substantial revenue and still encounter mortgage qualification challenges. Conversely, a lower taxable income figure does not tell the entire qualifying story.
Gross business revenue is not the same as qualifying income, but the analysis also goes beyond the taxable income figure alone. Depending on the business structure and loan program, the review may include personal and business tax returns, current financial statements, allowable add-backs such as depreciation, earnings trends, and the stability of the income.
Divorce can create additional complications when the settlement changes business ownership or access to business income. Those changes should be evaluated before relying on that income to support a refinance or home purchase.
Alternative Documentation May Provide Another Path
When traditional income documentation does not support qualification, alternative programs may offer additional options. Depending on the client’s circumstances, these may include bank statement programs or asset-depletion programs that use eligible verified assets to calculate qualifying income.
These are different documentation paths—not an exemption from mortgage qualification. Program eligibility, terms, and documentation requirements still apply.
Separately, cases involving investment properties or other qualifying business purposes may warrant a review of business-purpose financing. Eligibility depends on the loan’s purpose, property occupancy, and applicable program requirements.
Planning Tip: Have the income reviewed before setting the refinance deadline, particularly when a business interest is being divided or transferred as part of the settlement.
Our articles on self-employment income and divorce mortgage planning and alternative income documentation options explain these considerations in greater detail.
3. Credit Scoring Should Be Part of the Initial Mortgage Conversation
Credit concerns should be evaluated early—not only after a client has been denied financing or is approaching a court-ordered refinance deadline.
Revolving balances, payment history, joint obligations, and authorized-user accounts can all affect the mortgage credit profile. A targeted review helps identify which issues need attention and how they may affect the available loan options.
Credit Simulation and Rapid Rescoring

Our review may include credit simulation to evaluate how specific account changes could affect mortgage credit scores. After the recommended actions are completed and supporting creditor documentation is obtained, rapid rescoring may help expedite verified account updates in as little as 5 days!
Rapid credit rescoring is not credit repair. It does not erase accurate negative history or guarantee a particular score increase or loan approval. Its purpose is to help the credit report reflect documented changes without waiting for the next regular reporting cycle.
Planning Tip: When credit changes are needed, account for the time required to complete the actions, obtain documentation, and update the credit report.
For the process and documentation involved, read Part 2 of our Rapid Credit Rescoring in Divorce series.
4. Settlement Language and Refinance Deadlines Need to Match the Mortgage File
These financing considerations also connect directly to how the marital settlement agreement addresses debt and timing.
When assigning responsibility for a joint debt, use what I refer to as “linking language” to connect the obligation to the specific account appearing on the credit report. This may include the creditor’s name, a partially masked account number, and the spouse responsible for repayment.
The applicable loan program determines whether the assigned payment can be excluded from mortgage qualifying ratios and what documentation is required.
Timing deserves the same attention. A client who needs credit updates or additional self-employment documentation may have a different path to closing than a client whose file is already ready for underwriting.
Drafting Tip: Before finalizing a refinance deadline, identify the qualification and documentation steps that still need to be completed. The deadline should reflect the actual borrower and transaction, not a generic number of days.
For more on debt assignment and mortgage qualification, read Divorce and Joint Debts: What Family Law Attorneys Must Know for Mortgage Qualification.
Second Opinion Service (SOS): Review the Mortgage Strategy Before Settlement
Our Divorce Lending Practice Group offers a complimentary Second Opinion Service (SOS) for family law professionals and divorcing homeowners who need help evaluating a mortgage-related scenario.
Depending on the circumstances, our review may include:
- Divorce refinance and equity buyout options
- Self-employed income analysis and alternative documentation programs
- Credit report review and simulation of potential scoring changes
- Debt-to-income calculations and jointly held obligations
- Mortgage-related settlement provision review and anticipated closing timeline readiness
The objective is to identify potential financing problems while there is still an opportunity to address them—before settlement terms are finalized or a refinance deadline becomes difficult to meet.
Continuing the Conversation Beyond Bench Bar
I appreciated the opportunity to support this year’s HCBA Bench Bar and speak with family law attorneys at our table. Thank you to HCBA for bringing the legal community together and to the professionals who continue to make divorce mortgage planning part of their client discussions.
Need help pressure-testing a refinance, self-employed income situation, or credit concern before settlement? Our Divorce Lending Practice Group is available to review the mortgage options and identify potential qualification issues.
We also offer customized in-office and virtual presentations for family law firms. Contact our office to arrange a session focused on the mortgage-related issues your team encounters most often.
Call/Text: 813-935-8330
Office: 800-806-9836 Ext. 280
Email: SeanS@MPLX.org
Sean A. Stephens, Esq., CMB®, CDLP®
President | Chief Legal Officer
Metroplex Mortgage Services, Inc. | NMLS# 185264
Individual NMLS# 185288
And don’t forget—download your complimentary copy of the Divorce Lending Blueprint for Success to keep as a resource for both you and your clients.
Legal Disclaimer: The information provided on this blog does not, and is not intended to, constitute legal advice; instead, all information, content, and materials available on this site are for general informational purposes only. No representations or warranties of any kind, express or implied, are made about the completeness, accuracy, reliability, or availability of this information. Metroplex Mortgage Services, Inc., is not a law firm and does not provide legal services. Sean A. Stephens is a licensed attorney and member of The Florida Bar #1027099, California State Bar #332960, and Chief Legal Officer for Metroplex Mortgage Services, Inc.


