


3 Trending Divorce Mortgage Topics for Florida Family Law Attorneys
Hillsborough County Bar Marital & Family Law Joint Luncheon and Recap: Trending Topics in Divorce Mortgage Planning
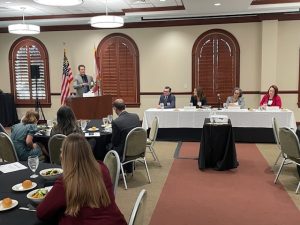
As the sponsor at this week’s Hillsborough County Bar’s Family Law Joint Luncheon, I had the privilege to provide opening remarks and sharing three trending divorce mortgage topics impacting the family law professionals and their clients.
The luncheon included a CLE program titled “Handling Difficult Clients and Avoiding Common Pitfalls,” featuring a distinguished panel:
- Rachael Rudin, Rachael Ledet Rudin, P.A.
- Sarah Kay, Kay Family Law PLLC
- Joan Montagno, Montagno Mediation, LLC
Moderator: Cory Brandfon, Harris, Hunt & Derr, P.A.
This engaging event provided valuable insights into managing the human dynamics of family law practice.
As both a member of the Marital & Family Law Section and a Certified Divorce Lending Professional (CDLP® ), I was honored to open the program with  remarks on divorce mortgage planning—and why these issues matter to attorneys, mediators, and their clients.
Divorce Mortgage Planning: Trending Topics for Family Law Professionals
As both a member of the Marital & Family Law Section and a Certified Divorce Lending Professional (CDLP® ), my goal is to continue providing value by sharing insights on trending divorce mortgage planning topics that impact Florida’s family law community.
The topics I reviewed included the following:
1. Credit Qualifying – Authorized User Accounts
Why it matters:
An authorized user is someone added to another person’s credit card account, but is not responsible for repayment. However, late payments or adverse activity will still appear on their credit report and impact their scores.
Depending on the creditor, authorized users can unilaterally remove themselves from the account or it may have to be done via the primary cardholder.
On the other hand, joint obligations generally remain on both credit reports until refinanced or paid off, which can impact both debt-to-income ratios and credit scores. Removing an authorized user may help improve debt-to-income ratios, credit scores, and overall mortgage qualifying ability.
 Drafting Tip:
Where applicable, consider requiring the primary account holder to remove the authorized user as part of the settlement process.
2. Self-Employed Income Calculation
Why it matters:
For self-employed clients, mortgage qualification hinges on how income is documented—the right path preserves options.
What works:
- Traditional Documentation includes 1040s, Schedule C, business returns (1120S/1120/1065), K-1s,
- YTD P&L, and balance sheets.
- Alternative Documentation examples include bank statement programs (12–24 months), asset depletion, or business purpose loans as options when traditional financing won’t qualify.
Involving a CDLP® early in the process helps align settlement terms with underwriting guidelines, preserving mortgage and refinance options post-divorce. These distinctions can make or break refinance approval during divorce.
3. Appraisal Contingency Clauses
Why it matters:
Lenders are required to use independent appraisers who follow Appraisal Independence Requirements (AIR) which is separate from any divorce appraisal or other valuation obtained during negotiations. This also means the lender’s appraisal may differ from a divorce valuation obtained during negotiations.
If that happens, the available equity for buyouts or settlements could change significantly and may also delay the timing of finalizing settlement funds.
Drafting Tip:
Consider an appraisal contingency clause that allows negotiated terms to adjust if the lender’s valuation does not match the agreed-upon figure in the MSA.
Proud to Support Our Family Law Community
Even if you weren’t able to attend, these insights apply to family law practices across Florida’s legal community. It was a pleasure connecting with so many dedicated professionals at this event. These discussions highlight why collaboration between legal and lending professionals is so important when property and financing intersect in divorce cases.
As Chair of our Divorce Lending Practice Group at Metroplex Mortgage Services, we appreciate the opportunity to be your trusted resource for mortgage planning, refinance, and purchase solutions.
Let’s Stay Connected
If your client intends to keep the home, early planning makes all the difference. Contact us to review options, assess qualifying limits, and ensure enforceable, mortgage‑compliant terms.
Call/Text: 813‑935‑8330
Office: 800‑806‑9836 Ext. 280
Email: SeanS@MPLX.org
📅 Now Scheduling In‑Office & Virtual Presentations
If you’d like to learn more about how divorce mortgage planning can support your clients, or if your firm is interested in hosting an in-person or virtual Lunch & Learn presentation, I’d be happy to coordinate a custom session. Customized sessions for Florida family law firms on:
- Equity‑buyout refinance planning
- Purchase options and down‑payment requirements
- Credit scores and debt‑to‑income ratios
- Best practices for drafting enforceable mortgage‑related provisions
Contact our office today to reserve your preferred date and time.
Sean A. Stephens, Esq., CMB®, CDLP®
President | Chief Legal Officer
Metroplex Mortgage Services, Inc.
Legal Disclaimer: The information provided on this blog does not, and is not intended to, constitute legal advice; instead, all information, content, and materials available on this site are for general informational purposes only. No representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, or availability to this information. Metroplex Mortgage Services, Inc. is not a law firm and does not provide legal services. Sean A. Stephens is a member of the California State Bar #332960 and Florida Authorized House Counsel #1027099 for Metroplex Mortgage Services, Inc. Florida Authorized House Counsel may provide legal services in Florida solely to the employing business organization, but is not authorized to practice law in the state of Florida and is not a member of the Florida Bar.


